Banking & Financial Services
Third-party onboarding is judged on the evidence you kept.
Banks, insurers and payment firms onboard technology vendors, outsourcing providers and professional advisers under supervisory expectations for third-party risk. Every approval must be explainable later.
Supplier relationships
Who you onboard, and what you need from them.
Typical suppliers and documentation in banking & financial services. In Skuvet these become supplier categories with their own requirements.
Typical suppliers
- Technology and SaaS vendors
- Outsourcing and service providers
- Professional advisers
- Facilities and operational vendors
Information and documents
- Legal entity and ownership information
- Sanctions and watchlist screening results
- Security questionnaires and attestations
- Contracts, insurance and financial information
The challenge
What makes onboarding hard in banking & financial services.
Evidence lives in inboxes
When an auditor asks what was checked before a vendor was approved, the answer is spread across email, shared drives and memory.
Onboarding and third-party risk run separately
Procurement onboards the vendor while risk runs its own assessment, and the two records drift apart.
Separation of duties is hard to prove
Policies require that the requester cannot approve their own vendor. Showing that it never happened takes manual reconstruction.
How Skuvet applies
An example onboarding workflow.
An illustration of how a banking & financial services organisation could configure Skuvet. Stages, checks and approvers are set to your own policies.
The vendor provides entity, ownership and contact details through a controlled portal.
Registry checks and sanctions screening run on submission; results and timestamps are stored with the record.
Exceptions and risk findings are reviewed by named people. Requesters, reviewers and approvers are kept distinct.
An evidence pack per vendor shows what was checked, when, by whom and with what result.
Products and catalogues
Product onboarding rarely applies. Skuvet is used here for vendor onboarding, verification and approval, and complements an existing third-party risk platform where one is in place.
Supplier & vendor onboarding →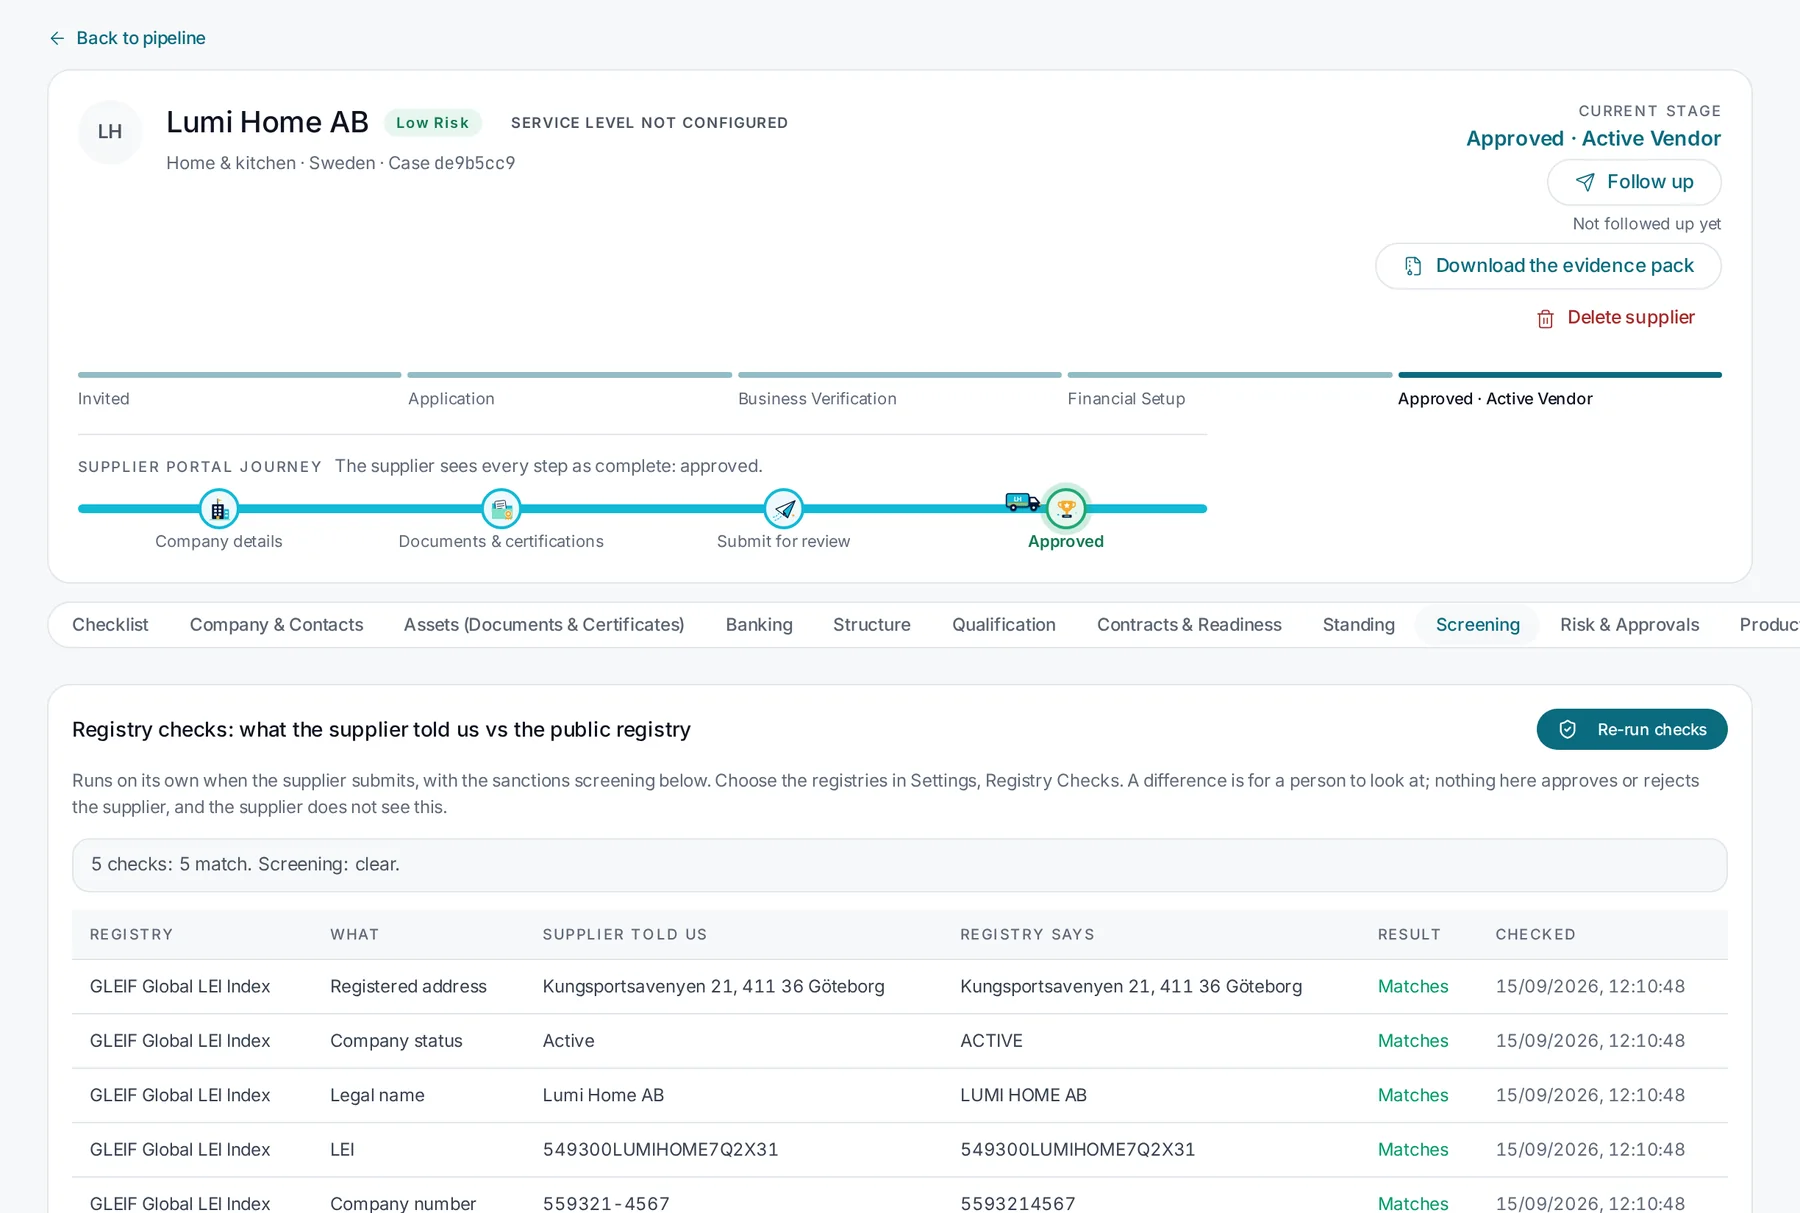
Skuvet supports evidence collection and approvals. It does not replace a firm's third-party risk methodology or regulatory judgement.
Other industries
The same platform elsewhere.
Experience Skuvet
See how Skuvet would work for banking & financial services.
Tell us about your suppliers, documents and systems. We will tailor the demonstration to your process.